
Becoming an NRI can change how you should maintain your existing Indian bank account. Continuing to use a regular resident savings account after your residential status changes may not be appropriate. Understanding when you need an NRI account and whether your existing account should be redesignated as an NRO account can help you manage your finances in line with applicable requirements.
Can an NRI continue using a resident savings account?
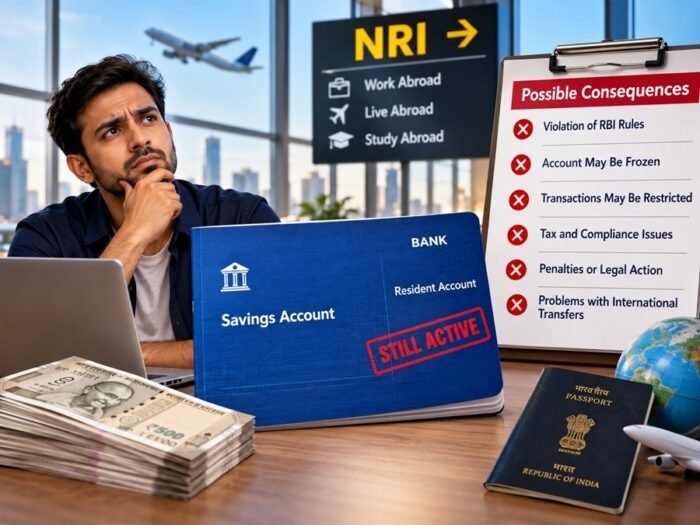
You should not assume that a resident savings account can continue unchanged after you become an NRI.
Once your residential status changes, inform your bank and check the applicable process for updating your account. Depending on your circumstances, your existing resident savings account may need to be redesignated as an NRO account.
Taking action promptly can help ensure that your account reflects your current residential status and that your Indian-source income is managed through the appropriate banking arrangement.
Why does residential status matter?
Resident and NRI banking arrangements are subject to different rules. Your residential status can affect how your Indian bank accounts are maintained and how different sources of income are handled.
If you move abroad and become an NRI, you may continue to have financial commitments and income in India, such as:
- Rental income
- Pension
- Dividends
- Interest income
- Property-related expenses
An appropriate NRI account can help you manage these financial requirements while living abroad.
What happens to your existing savings account?
If you become an NRI, your existing resident savings account may need to be redesignated according to the bank’s applicable procedures.
An NRO account is generally used by eligible NRIs to manage permitted income arising in India. This can include rental income, pension, dividends, interest and other permitted Indian-source receipts.
Instead of continuing to operate a resident account without updating your status, contact your bank and determine the appropriate account arrangement.
Should you open an NRO account?
An NRO account may be appropriate if you continue to receive income from India after becoming an NRI.
You may consider one if you:
- Receive rental income from Indian property
- Receive pension in India
- Earn dividends from Indian investments
- Receive interest income
- Need to manage regular expenses in India
The exact treatment of income and account requirements depends on applicable regulations and bank terms.
What should you do after becoming an NRI?
If your residential status changes, review your Indian banking arrangements promptly.
A practical approach is:
- Inform your bank about your change in residential status.
- Check whether your resident savings account needs redesignation.
- Determine whether an NRO account is appropriate for your Indian income.
- Consider an NRE account for eligible overseas earnings.
- Update your KYC and overseas contact details.
- Review the applicable account terms and charges.
- Keep your banking and tax records updated.
Completing these steps can help avoid unnecessary complications with account operations.
Conclusion
If you become an NRI, you should not assume that your existing resident savings account can continue unchanged. Inform your bank, update your residential status and determine whether an NRO account is appropriate for managing permitted Indian-source income. An NRE account may also be relevant for eligible overseas earnings. Choosing the right NRI account arrangement and keeping your banking information updated can help you manage your Indian finances more effectively while living abroad.
FAQs
1. Can an NRI continue using a resident savings account?
Inform your bank when your residential status changes, and check whether the existing account needs to be redesignated or converted under applicable requirements.
2. Should a resident savings account be converted to an NRO account?
If you become an NRI and continue to receive permitted income arising in India, an NRO account may be appropriate. The bank can confirm the applicable process.
3. What is an NRO account used for?
An NRO account is generally used by eligible NRIs to manage permitted income arising in India, such as rental income, pension, dividends and interest.
4. Do NRIs need both NRE and NRO accounts?
Not necessarily. The right account depends on your income sources and financial needs. Eligible NRIs may maintain both when they need to manage overseas and Indian-source income separately.
5. Can I manage an NRI account from abroad?
Many banks provide digital banking facilities that allow eligible customers to manage an NRI account remotely, subject to the bank’s available services and applicable terms.